
Upgrade
- Rating
- 4.4
- Downloads
- 1.00M
- Content Rating
- Everyone
Upgrade - Screenshots
Pros
- Clear upgrade paths make progression easy to understand.
- New features can significantly improve the overall user experience.
- Regular improvements help keep the app feeling current.
- Upgrade options may provide better performance and convenience.
- Useful for users who want more control over available features.
Cons
- Some upgrades may require additional purchases or subscriptions.
- The best features can be difficult to access without upgrading.
- Frequent upgrade prompts may interrupt the normal experience.
- Changes after upgrading may take time to learn and adjust to.
- Value can vary depending on how often you use the app.
Upgrade - Description
- App Name
- Upgrade
- Package Name
- com.upgrademobile
- Developer
- Upgrade, Inc.
- Category
- Finance
- Last Updated
- Mar 21, 2019
- Version
- 1.33.0
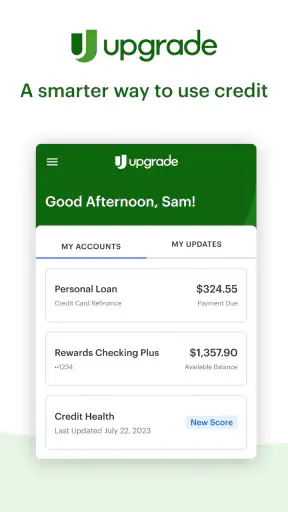
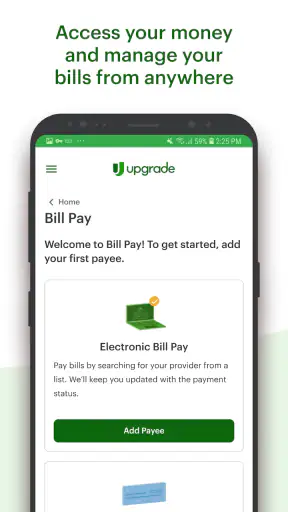
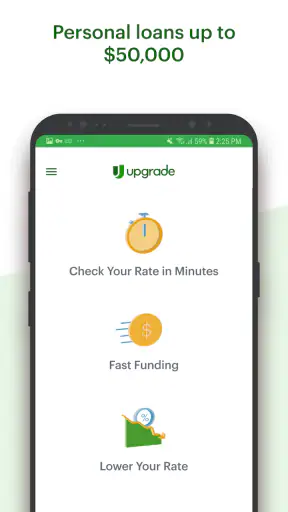
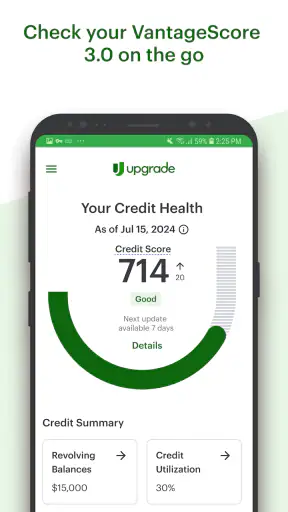
I approached Upgrade as a finance app rather than a simple banking shortcut. Its focus is personal loans, cards, and rewards checking, so the important question is not whether it looks polished, but whether its choices are clear enough when money and personal information are involved. After spending time with it, I see a useful mobile starting point for people comparing borrowing and everyday account options, although it deserves a careful reading before you accept anything.
Upgrade, Inc. develops the app, which is free to install and available to everyone by age rating. It has reached more than a million installs and holds a 4.4 average from roughly thirty thousand ratings, with about four thousand written reviews. Those figures suggest that it has attracted a substantial audience, but they should not replace your own checks. A finance app can be widely used and still be the wrong fit for one person’s borrowing needs, repayment comfort, or privacy expectations.
What I looked for before trusting a finance app
My first test was whether the app’s purpose was understandable. Upgrade brings several financial products into one place: personal loans, cards, and rewards checking. That combination can be convenient, especially if you would otherwise move between separate lender, card, and checking apps. It can also make the experience feel more like a product marketplace than a neutral budgeting tool, so I paid attention to where the app asks for information and when it presents a decision.
The distinction matters. A calculator or expense tracker can often be used without making a financial commitment. An app centered on loans and credit products naturally reaches more sensitive moments, including identity checks, income details, account connections, and repayment decisions. My advice is to treat every application screen as a point where you should pause, read the wording, and decide whether the next step is necessary for what you actually want to do.
The app runs on iOS twelve or later, and its current version is 1.33.0. That makes compatibility easy to check before downloading, but an up-to-date operating system is only the beginning of responsible use. I would still keep device security enabled, use a strong device passcode, and avoid reviewing loan information on a shared or public screen.
One useful way to approach Upgrade is to choose a single task before opening it. If you are exploring a personal loan, stay focused on understanding that route. If you are considering a card or rewards checking, examine that product separately. This prevents the convenience of one app from turning into a rushed decision across several financial products.
Clearer choices matter more than a polished dashboard
In my experience, the strongest sign of trust is not a colorful balance screen. It is whether the app lets me understand what I am being asked to provide, what I am agreeing to, and what happens next. For Upgrade, that means reading each product’s terms instead of treating an approval-style screen as a recommendation. A loan can solve an immediate problem while creating a longer repayment obligation, and a card can be useful while still costing more than expected if the balance is carried.
I would also separate “checking what may be available” from “accepting an offer.” Those are different decisions. When an app presents a pathway from an initial inquiry to a formal application, I want the boundary between them to be obvious. If the wording is unclear, I would stop and look for the explanation before submitting anything. That habit is more valuable than trying to move through the screens as quickly as possible.
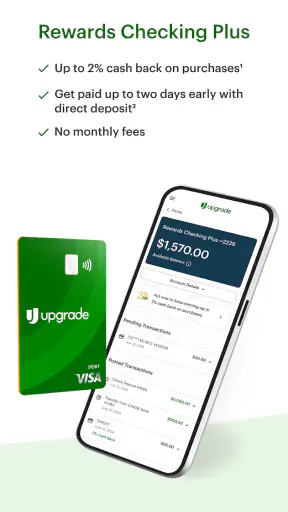
The same caution applies to rewards checking. Rewards can make an account sound attractive, but I would judge the account by its everyday conditions, access, transfer process, and any requirements shown in the current terms. A reward is only useful if the account fits how you already manage money. I would not change direct deposits, bill payments, or emergency savings arrangements until I had read those conditions carefully.
Where personal information becomes especially sensitive
Finance apps necessarily deal with information that can affect a person’s financial life. In Upgrade, the most sensitive moments are likely to be the ones connected with applying for credit, verifying identity, evaluating eligibility, or linking financial activity. I am deliberately careful here: I do not treat a request for information as automatically suspicious, but I also do not enter details merely because a screen makes the request feel routine.
Before continuing, I would read the app’s visible privacy and consent explanations, check which information is required for the specific product, and confirm that I am using the official application from the expected developer, Upgrade, Inc. I would also review the device’s permission controls rather than approving every prompt automatically. The practical rule is simple: give the app only the access and information you understand and genuinely need for the task.
Account linking deserves extra attention. Connecting an existing account may make verification or money movement easier, but it also creates a relationship between services that you should understand before approving. I would check the institution name, the purpose of the connection, and whether the app gives a clear way to manage or remove that connection later. If I could complete my intended task without linking another account, I would compare both paths instead of assuming linking is mandatory.
Notifications are another small but meaningful privacy choice. A balance alert can be helpful, while a message that reveals financial activity on a lock screen may be uncomfortable. I would configure notification previews at the phone level and inside the app if those controls are offered. That is particularly important for anyone who shares a home, uses a work phone, or regularly leaves the device visible.
How I would use it in an everyday situation
Imagine that an unexpected household repair arrives while your current cash flow is tight. I would not open Upgrade and immediately choose the first borrowing option. I would first write down the amount needed, the date the expense must be paid, and the monthly payment I could handle without relying on another loan or a card balance. Then I would use the app to explore the relevant personal-loan route, carefully distinguishing an initial check from a final commitment.
At each stage, I would record the key terms in my own notes: the amount, repayment length, total cost, payment timing, and any conditions shown before acceptance. I would compare that result with a credit-union offer, a bank option, or a payment plan from the service provider. The app can make one option easier to investigate, but convenience is not proof that it is the least expensive option.
If the proposed payment only works when everything goes perfectly, I would walk away. A realistic budget should allow for ordinary surprises, not just the month in which the application is made. This is where Upgrade may be useful as a comparison starting point, but it should not be treated as a substitute for a written repayment plan.
Practical workflows that make the app safer to use
My first recommended workflow is to separate exploration from commitment. Use one session to understand the available product and another to make a decision after comparing alternatives. This creates a cooling-off period and reduces the chance that a time-sensitive-looking screen will push you into borrowing before you have considered the full cost.
My second tip is to capture the exact terms you see at the moment you are evaluating an offer. Do not rely on memory or a later dashboard summary. Keep your own record of what you understood, especially if the decision affects recurring payments. If the wording changes between stages, that is a reason to ask for clarification rather than assuming the difference is unimportant.
My third tip is to review account access after setup, not only during setup. Check the phone’s permissions, notification behavior, linked-account choices, and any available security settings. I would also avoid saving sensitive information in screenshots or unprotected notes. A finance app can have sensible controls, but the safety of the whole setup still depends on the device and habits around it.
A fourth useful habit is to give each product a separate purpose. If you use the checking side for routine spending, do not confuse its balance with money available for a loan payment. If you use a card, decide whether it is for planned purchases or emergency use before the first transaction. Keeping those roles distinct makes the app easier to understand and reduces accidental overspending.
Where Upgrade is stronger than familiar alternatives
Compared with using a traditional bank for checking, a separate card issuer for credit, and another lender for a personal loan, Upgrade offers a more concentrated experience. That can save time for someone who wants to investigate several related options without maintaining several apps. The single finance-oriented home base is also useful for a person who prefers mobile-first account management.
It may be particularly appealing to someone who is comparing a loan and a card at the same time, provided they can resist treating every available product as necessary. The app’s broad purpose makes it easier to begin that comparison in one place. For a user who values a single brand relationship and straightforward digital access, that is a genuine advantage.
However, a conventional bank may be better for someone who wants established branch access, a broad set of deposit services, or an existing relationship with a local adviser. A credit union may deserve attention when its lending terms are more suitable. A dedicated budgeting app may be the better choice for someone who wants spending analysis without being drawn toward borrowing products.
There is also a behavioral trade-off. Seeing loans, cards, and checking together can help you understand your options, but it can also make borrowing feel like a normal extension of everyday account management. I would recommend Upgrade more readily to a disciplined comparison shopper than to someone who tends to solve recurring shortfalls with new credit.
Who should take extra care before signing up
I would be cautious if you are looking for a completely free budgeting tool, because Upgrade’s main focus is broader financial products rather than only expense tracking. I would also slow down if your income changes frequently, your existing debts are difficult to manage, or you are considering a loan to cover another loan payment. In those situations, a nonprofit debt adviser or a direct conversation with your current financial institution may be more appropriate.
People who dislike managing several product terms in one app should compare the experience with a simpler provider. Combining services is convenient, but it means you must keep track of different conditions and purposes. I would not choose it solely because the application is free; the financial products themselves need to make sense for your situation.
Privacy-conscious users should make their own permission and consent review part of setup. I appreciate the ability to make deliberate choices, but no app can decide your comfort level for you. Read the visible explanations, decline access that is not necessary for your chosen task, and revisit those decisions if your use changes.
My measured verdict after reviewing the experience
Upgrade is a reasonable finance app for exploring personal loans, cards, and rewards checking in one mobile environment. Its 4.4 average and audience of over a million installs show that it is not an obscure experiment, while its free download and Everyone age rating make it easy to try. Still, those points say more about reach and accessibility than about whether a specific offer is right for you.
I would recommend it as a comparison and account-management starting point for an adult who reads terms carefully, keeps borrowing within a written budget, and is willing to review privacy choices during setup. I would not recommend opening it with a vague goal such as “find money quickly.” That mindset makes it too easy to overlook repayment pressure, product conditions, or the amount of personal information involved.
The app’s best quality is its concentration: loans, cards, and checking can be considered from one place. Its main weakness is the same concentration, because several financial decisions can sit close together and feel equally easy to start. My final advice is to use it deliberately, compare any borrowing option with alternatives, document the terms you accept, and keep control of linked accounts and notifications. Used that way, Upgrade can be practical; used impulsively, its convenience is not enough to make a financial decision safe.
FAQ
What is Upgrade, and what can I use it for?
Upgrade is a financial services app designed to help users manage personal finances through products such as personal loans, checking-style accounts, payment cards, and credit-building tools, depending on eligibility and availability. After installing it, you can review potential offers, monitor account activity, make payments, and access financial information from one place. Features may vary by location and approval status.
Is Upgrade free to download and use?
The Upgrade app is generally free to download, but using its financial products may involve costs. Depending on the service you choose, you could encounter interest charges, origination fees, late-payment fees, or other applicable charges. The app should display important terms before you accept an offer, so review the annual percentage rate, repayment schedule, fees, and account requirements carefully rather than assuming every feature is free.
Can I qualify for an Upgrade loan or card directly through the app?
You can usually begin the application process through the Upgrade app, but approval is not guaranteed. Eligibility may depend on factors such as your credit history, income, debt obligations, identity verification, and other information requested during the application. Upgrade may perform a soft credit check for some initial offers, while accepting a product can involve a hard inquiry, so read the disclosures before submitting your final application.
Is Upgrade safe for managing personal and financial information?
Upgrade uses account security measures intended to protect personal and financial information, and the app may require passwords, verification steps, or device-based security features. However, no online service is completely risk-free. Use the official app store listing, keep the application updated, avoid sharing login codes, and contact support through official channels if you notice suspicious activity. Always review the privacy policy before creating an account.
What should I know before downloading and using Upgrade?
Before downloading Upgrade, confirm that its products are available in your country or state and that you meet the basic eligibility requirements. You will likely need to provide sensitive information, including identification and financial details, during registration or an application. Also check repayment terms, fees, credit-reporting practices, customer-support options, and cancellation procedures. The app can be convenient, but it should not replace careful comparison with other financial providers.


